Swatch card No. SW-9049 · cut November 5, 2026
Apparel ManufacturingMill spec card
Sanathan Textiles Q2 FY27 Revenue More Than Doubles to Rs 1,804 Crore
Sanathan Textiles posted Rs 1,804 crore ($190.1m) Q2 FY27 revenue, up 120.5%, as its Punjab facility ramped up and full production placement lifted EBITDA margin to 8.6%.
- Fiber
- Apparel Manufacturing
- Count
- 3 min read
- Cut
- Weight
- 677 words
Spec notes
- Q2 FY27 consolidated revenue rose 120.5% year on year to Rs 1,804 crore ($190.1m).
- Consolidated PAT jumped 204.5% to Rs 61.2 crore ($6.4m); EBITDA margin improved to 8.6% from 7.7%.
- Sequential revenue grew 35.2% from Rs 1,334.7 crore in Q1 FY27.
- Standalone EBITDA fell 11.7% sequentially to Rs 83.8 crore despite 22% standalone revenue growth.
- Management credited the Punjab facility ramp-up, higher utilisation and full production placement.
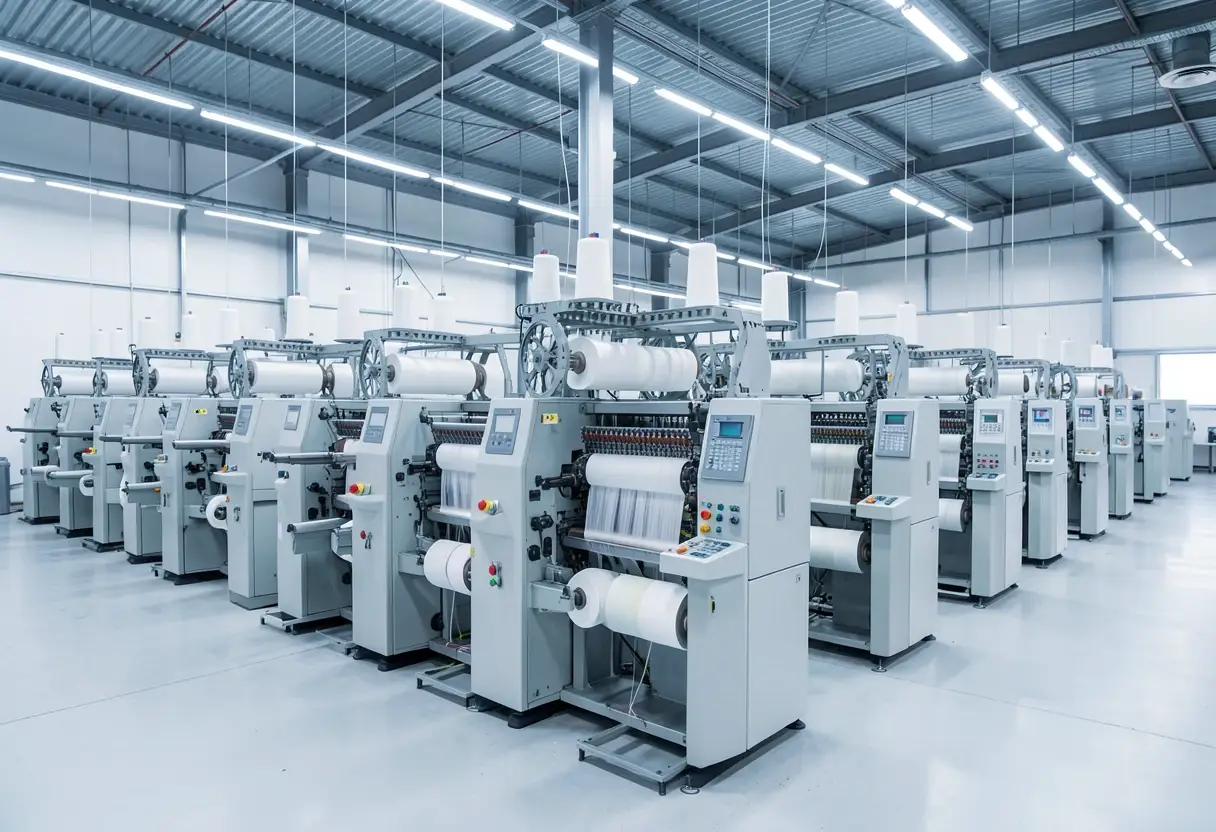
Sanathan Textiles reported consolidated revenue of Rs 1,804 crore (US $190.1 million) for Q2 FY27, a 120.5% year-on-year increase from Rs 818 crore (US $86.2 million) in Q2 FY26. The polyester filament yarn, cotton yarn and technical textile yarn manufacturer disclosed the figures for the September 2026 quarter this week.
Consolidated EBITDA rose 144.8% to Rs 154.7 crore (US $16.3 million), against Rs 63.2 crore (US $6.7 million) in the year-ago quarter. Consolidated profit after tax climbed 204.5% to Rs 61.2 crore (US $6.4 million), compared with Rs 20.1 crore (US $2.1 million) in Q2 FY26.
How strong was the sequential momentum?
Revenue grew 35.2% from Rs 1,334.7 crore (US $140.6 million) in Q1 FY27. EBITDA expanded 43.1% from Rs 108.1 crore (US $11.4 million). Consolidated EBITDA margin improved to 8.6% in Q2 FY27, up from 7.7% in Q2 FY26 and 8.1% in Q1 FY27. PAT margin reached 3.4%, against 2.5% in the year-ago quarter and 1.8% in the preceding quarter.
Management attributed the performance primarily to the continued ramp-up of its Punjab facility, higher capacity utilisation and full production placement. The company said the facility contributed to higher volumes and improved margins during the quarter. It did not disclose separate revenue, capacity or utilisation figures for the Punjab site — a gap that limits how precisely buyers and analysts can verify the capacity claim against the consolidated numbers.
What separates standalone from consolidated performance?
Standalone revenue stood at Rs 992.1 crore (US $104.5 million) in Q2 FY27, registering 29.3% year-on-year and 22% sequential growth. Consolidated revenue growth of 120.5% year on year ran significantly ahead of that standalone figure, indicating that subsidiary operations — rather than the legacy yarn business alone — drove the bulk of the expansion.
Standalone EBITDA told a weaker story. It stood at Rs 83.8 crore (US $8.8 million), down 11.7% from Rs 94.9 crore (US $10 million) in Q1 FY27, despite the 22% sequential rise in standalone revenue. Standalone EBITDA margin was 8.5%, contracting 320 basis points sequentially and 80 basis points year on year. Standalone PAT was Rs 58.7 crore (US $6.2 million), up 16% year on year but down 9.7% from Rs 65 crore (US $6.8 million) in Q1 FY27.
The divergence between rising standalone revenue and falling standalone EBITDA points to margin pressure at the core yarn business that the Punjab ramp-up, consolidated, has so far offset.
Why did demand recover from Q1?
Management said domestic demand remained strong during Q2 FY27, with customers returning to normal purchasing patterns as raw-material and product prices stabilised. Some customers had deferred purchases during Q1 FY27 amid disruptions in energy and raw-material markets caused by the West Asia conflict, the company said.
The recovery in buying activity, combined with the company's ability to place its entire production with customers, supported the sequential revenue growth. During Q1 FY27, management's stated priorities included securing raw-material supplies, ensuring production placement and maintaining uninterrupted plant operations at high efficiency — conditions it says normalised in the September quarter.
For buyers, the full placement claim signals available capacity has tightened at the producer level, which typically supports price discipline on yarn quotes rather than discounting.
What is the company's footprint?
Sanathan Textiles operates across polyester yarns, cotton yarns and yarns for technical textiles. Its manufacturing facilities are located in Silvassa and Punjab. The company offers more than 3,200 yarn products and nearly 50,000 stock-keeping units (SKUs) — a breadth that lets sourcing teams consolidate multiple yarn programmes with one supplier, but also implies complexity in lead-time management across that range.
Going forward, the company said it will focus on improving operational efficiency, expanding capacity and maintaining margins — stated intentions that remain to be measured against disclosed utilisation and margin figures in coming quarters.
via Apparel Resources (Source)
More from Marcus Bennett
Show full bio
Senior reporter covering money, funding and market shifts around fashion industry as a trade and business at The Fabric Brief.
248 articles